This page was last updated 11/6/2026 at 12:18 PM.
At the Palm Beach North Chamber of Commerce, advocating for a strong and thriving business community is one of our top priorities.
What Happens Next? Implementation & Legislative Developments
Although Amendment 3 has been approved by voters, several important details surrounding its implementation will be addressed through the legislative process.
On November 4, Governor Ron DeSantis announced plans to convene a special session of the Florida Legislature before the end of his term in January to address implementation of Amendment 3. The Governor has indicated that discussions could include additional homestead exemption provisions, limitations on alternative local taxes and fees, and potential assistance for local governments facing funding challenges.
As of November 6, dates for the special session have not been announced, and these additional policy proposals have not been enacted.
The Palm Beach North Chamber will closely monitor the special session, subsequent legislative activity, and decisions made by Palm Beach County and our local municipalities.
Key Dates & Developments
- November 3, 2026: Florida voters approve Amendment 3.
- November 4, 2026: Governor DeSantis announces plans for a special legislative session to address implementation.
- Before January 2027: Special legislative session anticipated; dates and legislation pending.
- January 1, 2027: Amendment 3 takes effect, including the increased $150,000 homestead exemption for qualifying properties and the reduced 5% non-homestead assessment-growth cap.
- 2027: State implementation measures and local government fiscal and budget planning will continue.
- January 1, 2028: The increased homestead exemption reaches $250,000 for qualifying properties.
What Does Amendment 3 Mean for Palm Beach North Businesses?
Amendment 3 introduces changes that could directly and indirectly affect businesses throughout Palm Beach North. While the reduced assessment-growth cap may provide greater predictability for some commercial property owners, the broader impact will depend in part on how state and local governments implement the amendment and respond to changes in property tax revenue.
Key areas the Chamber will be monitoring include:
Commercial Property Taxes: The reduction of the annual non-homestead assessment-growth cap from 10% to 5% may provide greater predictability for commercial property owners. However, future millage rates and other tax considerations will also influence actual property tax costs.
Commercial Leases & Operating Costs: Businesses operating under triple-net (NNN) leases may be particularly interested in how changes to property taxes, insurance, common-area expenses, fees, and assessments affect their total occupancy costs.
Local Taxes, Fees & Assessments: As local governments evaluate their budgets, the Chamber will monitor any proposed changes to millage rates, service fees, special assessments, or other revenue sources that could affect businesses.
Infrastructure & Public Services: Roads, transportation, public safety, stormwater systems, and other local services are essential to a strong business environment. The Chamber will track proposed changes to funding, service levels, and infrastructure investments.
Workforce Housing & Economic Development: Changes to property taxes and local government budgets may have broader implications for housing affordability, workforce availability, redevelopment, and future economic development initiatives.
Our goal is to help businesses understand how these changes may affect their operations while ensuring the business community has a voice in the decisions that follow.
What is Amendment 3?
Amendment 3 is an amendment to the Florida Constitution that will change how homestead and non-homestead properties are treated for property tax purposes. Approved by 62% of voters on the November 3rd election, the amendment will increase the homestead exemption for certain property taxes and lower the annual assessment-growth cap for non-homestead properties.
The measure could reduce property taxes for many property owners while also reducing the property-tax revenue that counties, municipalities and certain special districts would otherwise collect. How individual taxpayers and local governments are affected will vary.
What Changes Now?
| Issue | Current | Under Amendment 3 |
| Homestead exemption | $50,000 | $150,000 in 2027; $250,000 in 2028 for non-school levies, then adjusted for inflation |
| Non-homestead assessment cap | 10% annually | 5% annually |
| School taxes | Varies by municipality | Increased homestead exemption does not apply to school levies |
| Effective date | - | January 1, 2027 |
What Could This Mean for You?
Below are some potential considerations for Palm Beach North homeowners, business & commercial property owners, renters, and local governments to make when considering their vote on Amendment 3.
Homeowners
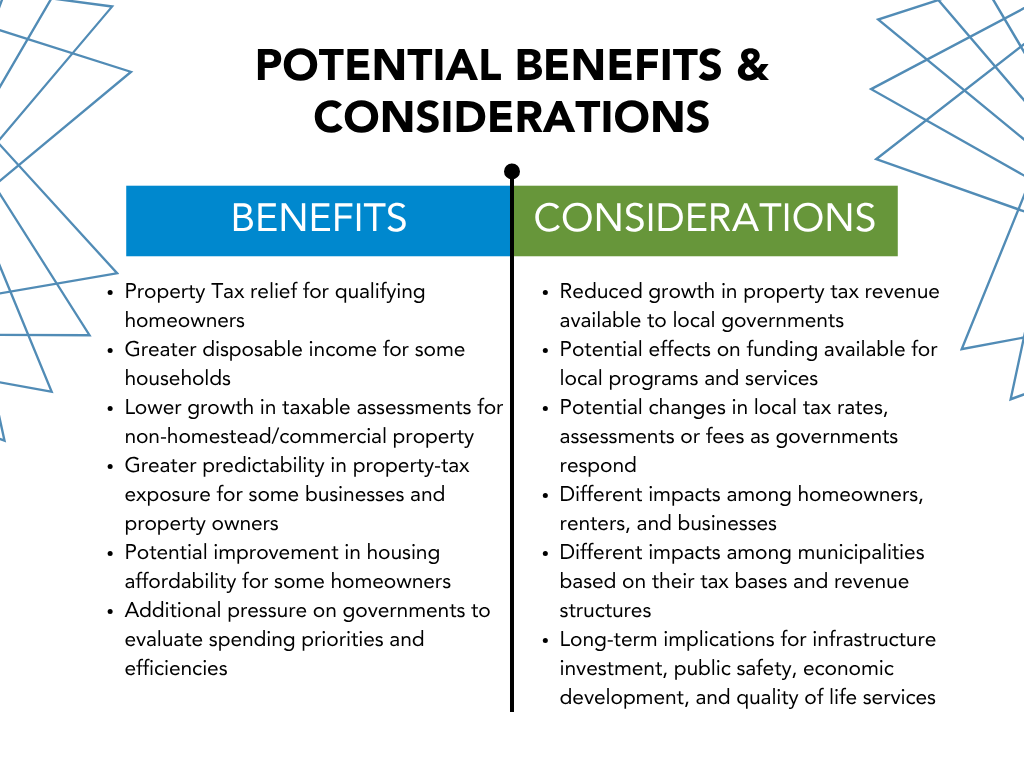
- Larger homestead exemptions could reduce non-school property taxes for qualifying homeowners.
- The amount of savings would vary based on assessed value, taxing jurisdiction and millage rates.
- School district property taxes would not receive the increased exemption.
- Future decisions by local governments could affect the ultimate impact on taxpayers, including millage rates and cutting of public services.
Businesses & Commercial Property Owners
- Non-homestead property would receive a lower annual assessment-growth cap, declining from 10% to 5%.
- This could provide greater predictability or slower growth in taxable assessments for certain commercial properties.
- At the same time, businesses should consider how local governments might respond to changes in property-tax revenue.
- Potential responses could include changes to millage rates, fees, assessments, spending or service levels, subject to applicable law and local decisions.
Renters
- Renters do not directly receive a homestead exemption on rental property, but changes in property taxation can affect the economics of rental properties.
- A lower non-homestead assessment cap could benefit owners of some rental properties, while broader changes in local government revenues or taxes/fees could also indirectly affect renters.
Local Governments & Community Services
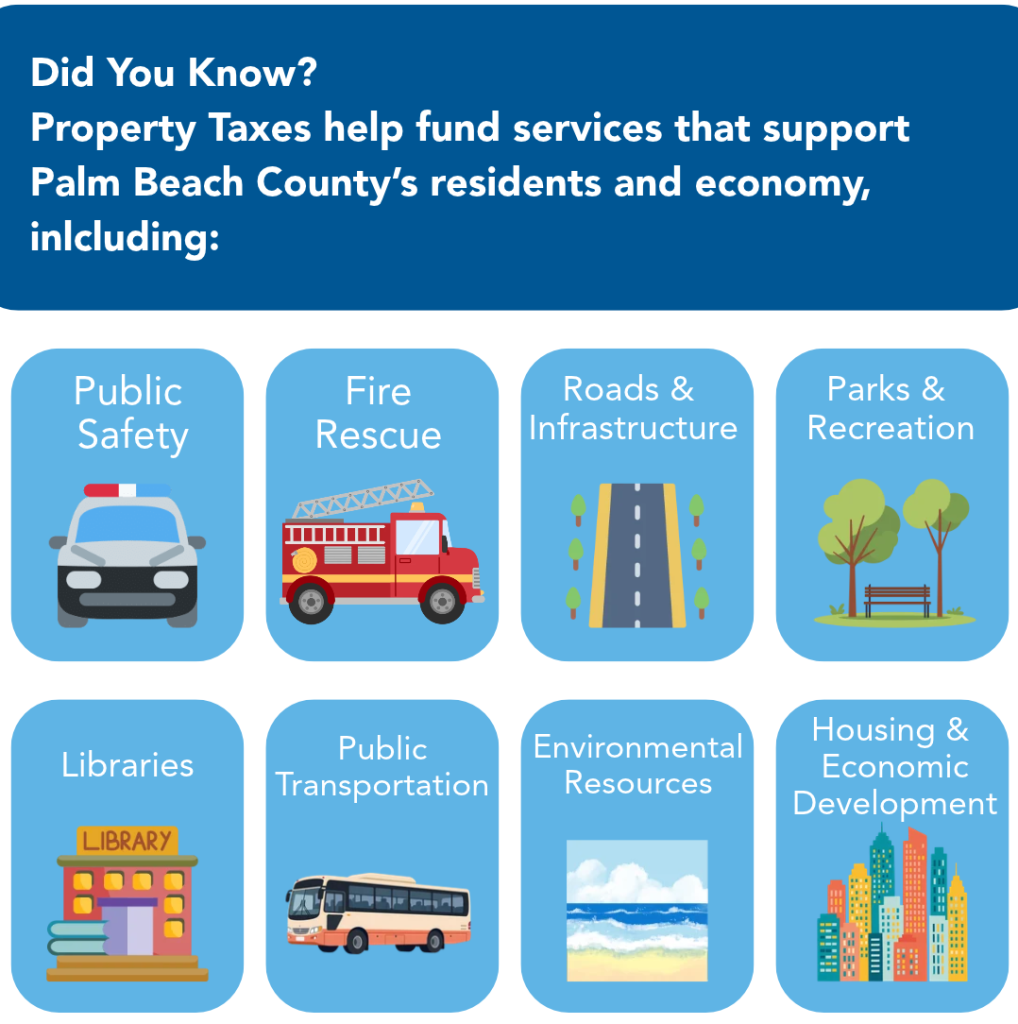
Property taxes are a major source of Palm Beach County revenue. The County's FY2026 budget includes approximately $2.167 billion in current property-tax revenue, including countywide, Fire Rescue, Library and debt millages.
Palm Beach County's budget identifies property-tax support for functions such as public safety, fire rescue, parks and recreation, roads and public works, and more.
For example, the FY2026 budget identifies approximately $110.6 million in net property-tax support for Palm Tran, $78.8 million for Parks & Recreation, $63.9 million for Engineering and Public Works, and $29.2 million for Public Safety.
Find the full County Budget here: https://discover.pbcgov.org/ofmb/budget/Pages/default.aspx
Amendment 3 Calculator
The Property Appraiser has created an Amendment 3 Homestead Calculator, which is now LIVE on the PAPA website at https://pbcpao.gov/calc-amend3-tax.htm. The calculator will let homesteaded property owners in Palm Beach County look up their property and see what their taxes may be in 2027 and 2028. It may also give them a look at the larger impact on the taxing authorities that they pay.
Why This Matters to Palm Beach North
Palm Beach North is home to a diverse group of municipalities, businesses, residents and public agencies, each with different tax bases, service needs and economic conditions.
Changes to Florida's property-tax system may affect each community differently.
For businesses, the issue extends beyond the amount paid on a property-tax bill. Local revenues help support infrastructure, public safety, transportation, parks, economic development and other services that contribute to the region's business climate and quality of life.
The Palm Beach North Chamber encourages voters and business leaders to consider both the direct tax implications of Amendment 3 and its potential long-term effects on the communities in which we live, work and do business.
Where Do Your Property Taxes Go?
For FY2026, Palm Beach County property-tax revenue was allocated across countywide government, Fire Rescue, the Library District and voted debt. The County also identifies property taxes as one of its major revenue sources.
The Potential Fiscal Impact to Palm Beach North Municipalities
City of Palm Beach Gardens Fiscal Analysis
- $24 Million Annual Revenue Loss: The City estimates the $250,000 homestead exemption would reduce its recurring property tax revenue by approximately $24 million annually beginning in year two.
- Public Safety Could Be Significantly Impacted: Approximately 57% of the City’s General Fund operating budget, excluding reserves, supports police and fire services. The City says revenue reductions could result in fewer police officers and firefighters, longer response times, and reductions in public safety technology, training, and specialized services.
- Potential Shift Toward Businesses & Rentals: About 40% of Palm Beach Gardens’ homesteaded residential properties have assessed values below $250,000 and could come off the City’s tax roll entirely. The City says this could shift more of the remaining property tax burden toward commercial and rental properties.
- Reduced City Services & Infrastructure Investment: Potential impacts identified by the City include reduced recreation programs and facility hours, higher user fees, less roadway paving and median maintenance, reduced stormwater maintenance, and reduced emergency preparedness.
- Impacts Could Extend to the Business Community: The City currently invests approximately $73 million in goods, services, contracts and capital projects. Officials say reduced revenue could mean fewer contracts, delayed or cancelled projects, and less public-sector spending with local vendors and contractors.
Watch the full impact report here: https://palmbeachgardensfl.new.swagit.com/videos/399397
Budget Workshop Presentation: https://www.pbgfl.gov/DocumentCenter/View/23862/Budget-Workshop-Proposed-Budget-2026-2027_Final-2
Village of North Palm Beach
- $4.7 Million Revenue Loss in 2027, Increasing to $6.87 Million in 2028: Based on the Palm Beach County Property Appraiser’s 2026 preliminary tax roll, the Village estimates Amendment 3 would reduce annual property tax revenue by approximately $4.7 million in 2027 and $6.87 million in 2028.
- Significant Dependence on Property Tax Revenue: Property taxes currently account for approximately 68% of the Village’s General Fund revenue, making them a critical funding source for municipal operations and services.
- Public Safety Services Could Be Impacted: Property tax revenue supports essential services, including police, fire, and emergency medical services. The Village identifies potential spending and service adjustments as possible responses to reduced revenue, although no specific reductions have been approved.
- Potential Reductions in Services & Infrastructure Investment: The Village identifies infrastructure, recreation, library services, and stormwater management among the programs supported by property taxes. Revenue reductions could require adjustments to municipal services, infrastructure investments, or other community programs.
- Potential Increased Costs for Businesses & Residents: To address revenue losses, the Village may consider adjusting millage rates, implementing or increasing fees and assessments, identifying alternative revenue sources, or reducing expenditures. These measures could create additional costs for local businesses and property owners.
Read more about the Village of North Palm Beach Fiscal Analysis: https://village-npb.org/1125/Understanding-Amendment-3
Local Impact Dashboard
| Community | Property Tax Revenue | % of General Fund | Key Services Supported | Local Analysis |
| Palm Beach Gardens | $105.66 M | 69.2% | Police, fire rescue/EMS, general government, planning, public works and other core municipal operations | PBG Budget |
| Jupiter | $34.6 M | ~43.8% | Public safety, general government, engineering/public works, culture, recreation, and parks | Jupiter Budget |
| Riviera Beach | $75.91 M | ~63% | Police/public safety, fire, parks and recreation, public works, planning/community development and general government | Riviera Beach Budget |
| North Palm Beach | $27.17 M | 67.9% | Public safety, public works, building & zoning, leisure services and general government | NPB Budget |
| Lake Park | $4.26 M operating ad valorem
* The General Fund also records $2.01 M in CRM-related ad valorem |
25.5% operating | General government, library, recreation/special events, community development, public works and contracted public-safety services | Lake Park Budget |
| Juno Beach | $4.60 M | 49.4% | Police/law enforcement, public works, planning, administration and general government | Juno Beach Budget |
| Tequesta | $13.63 M | 66.8% | Police and fire rescue, transportation/streets, parks and leisure services, general government and code compliance | Tequesta Budget |
| Palm Beach Shores | Pending verification | Pending verification | Pending verification | Pending |
| Mangonia Park | Pending verification | Pending verification | Pending verification | Pending |
| Palm Beach County | $1.543 B | ~74% of recurring General Fund revenue | Sheriff/public safety, constitutional officers, courts, County departments, parks, roads/infrastructure, environmental programs and capital needs | PBC Budget |
Questions Businesses Should Be Asking
- How could the lower non-homestead assessment cap affect my business property?
- How much of my municipality's budget currently comes from property taxes?
- Which local services rely most heavily on property-tax revenue?
- How might local governments respond if property-tax revenue declines?
- Could other taxes, fees or assessments change?
- What could this mean for infrastructure and transportation investment?
- How could the amendment affect housing affordability and workforce availability?
- Could the impacts differ between businesses that own and lease their property?